Alys Beach Insures Cheaper Than Rosemary Beach. Renting It Out Costs More.
September 24, 2026
September 24, 2026
An investor comparing two $3 million homes, one in Alys Beach and one a mile down the road in Rosemary Beach, will usually pull insurance quotes first. It's the easiest number to get and the easiest to compare. The Alys Beach quote comes back lower, often by several thousand dollars a year, and the temptation is to stop the analysis right there. Lower insurance, same price point, same beach. Case closed.
It isn't closed. The insurance gap is real and it comes from something you can see in the walls. But the governance system that produces that discount is the same system that quietly takes a much larger bite out of what you'll actually collect if you rent the place, and that second number rarely shows up until an owner is deep into their first season with the property.
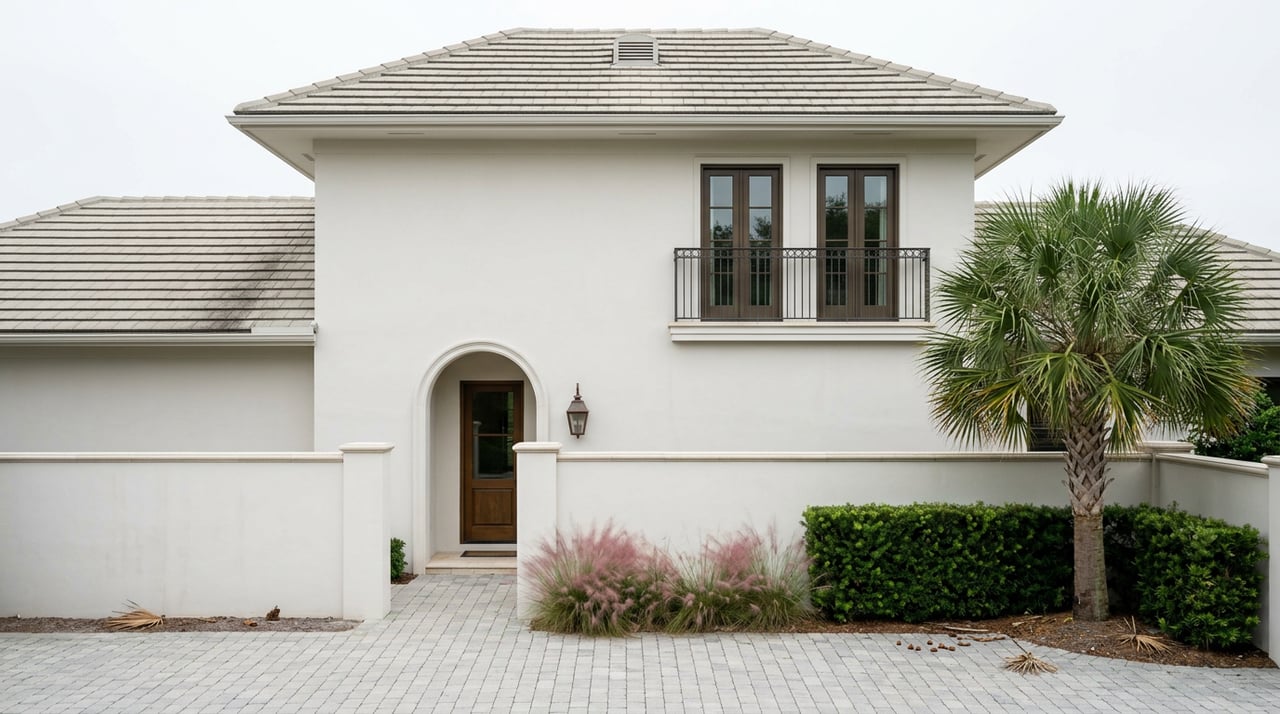
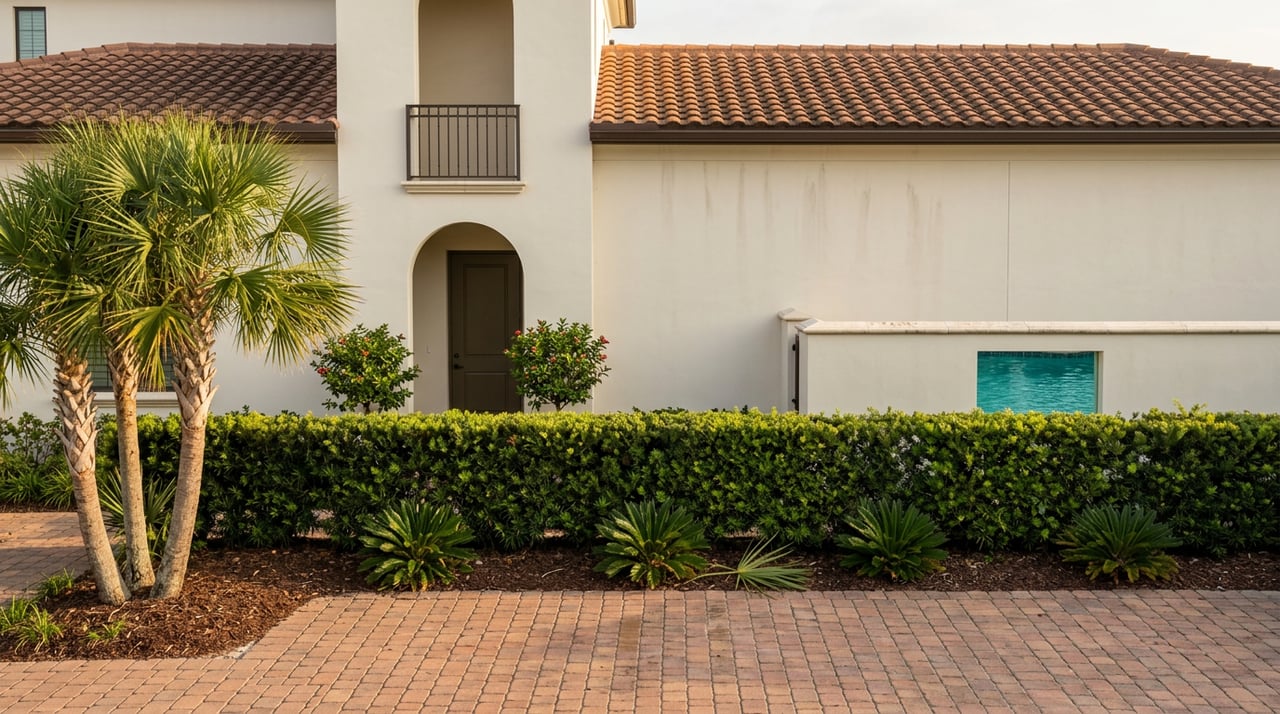
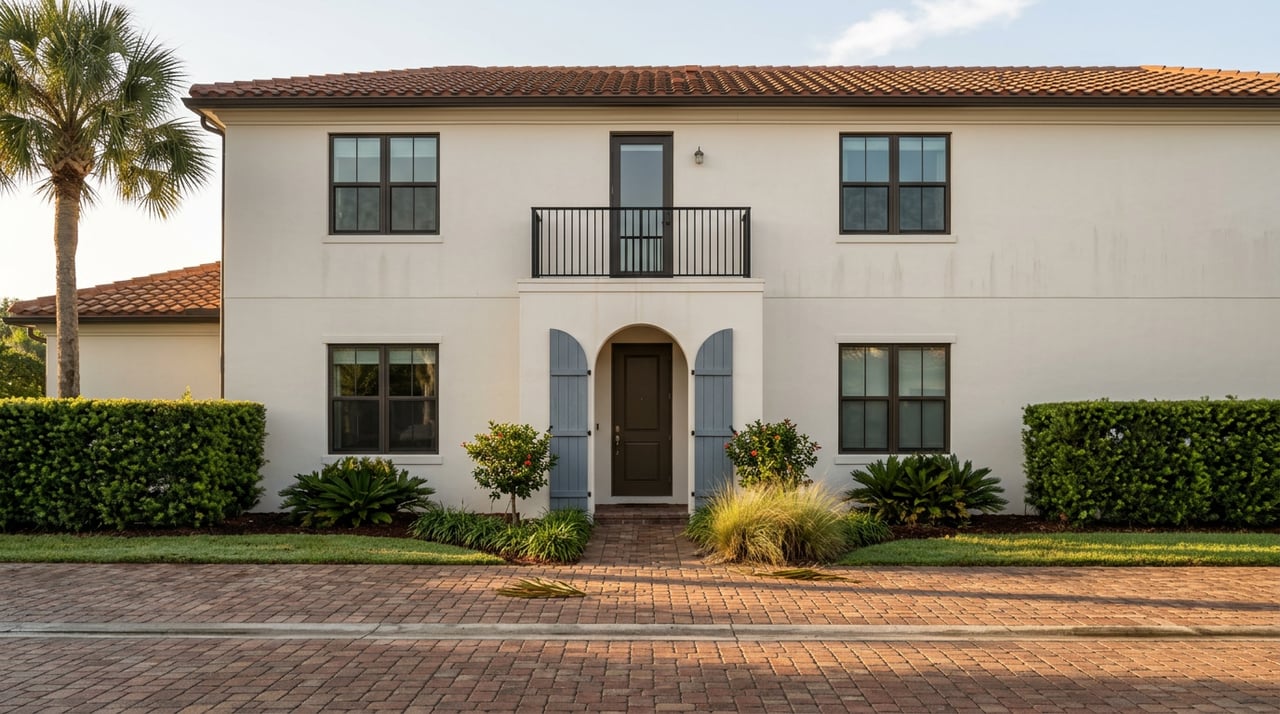
Alys Beach was built to the IBHS FORTIFIED for Safer Living standard from day one, which makes it the first community anywhere to construct every home this way. That means insulated concrete form and masonry walls, concrete tile roofs, impact-rated glazing, and rooflines with shallow eaves designed to resist wind uplift rather than catch it. Rosemary Beach, a mile away on the same highway, is built primarily in wood frame.
That construction difference shows up directly in a wind and hail premium. Reported figures for a $3 million home put Alys Beach's annual insurance in the $8,000 to $12,000 range, against roughly $12,500 to $16,000 for a comparable Rosemary Beach property. Independent research from the Urban Land Institute's Developing Urban Resilience project backs this up from the town's own planning side, describing the FORTIFIED standard as central to how Alys Beach secured the pricing and durability it markets today.
Call the midpoint gap around $4,000 to $5,000 a year. That's a legitimate, mechanical savings, not marketing. It just isn't the number that decides whether Alys Beach or Rosemary Beach is the better rental investment.
Rent a home in Rosemary Beach and you choose your own property manager, typically paying somewhere between 15 and 25 percent of gross booking revenue for the service. Rent a home in Alys Beach and you don't get that choice. Every owner who wants to rent is required to use the town's in-house management program, and multiple current sources report that fee at a flat 40 percent of gross, with no opt-out for outside management or self-listing.
That's not a rounding difference. It's a 15 to 25 percentage point gap on every dollar a guest pays, before a single insurance premium enters the conversation.
| Alys Beach | Rosemary Beach | |
|---|---|---|
| Rental management fee | Mandatory in-house, ~40% of gross | Owner's choice, ~15-25% of gross |
| Construction type | ICF/masonry, FORTIFIED-certified | Primarily wood frame |
| Annual insurance, $3M home (reported) | ~$8,000-$12,000 | ~$12,500-$16,000 |
| One-time capital contribution | Reported $30,000-$50,000 | Not applicable |
| Quarterly HOA dues (reported) | ~$3,000-$3,500 | Lower, single-family HOA typically runs a few thousand per year |
Figures for the capital contribution and quarterly dues vary by source and by the specific lot, so treat the ranges above as a starting point for due diligence, not a number to write into a contract.
Alys Beach's own rental program has reported gross annual bookings of roughly $120,000 to $145,000 for a three-bedroom courtyard home. Apply the fee structures above to that same range and the gap stops being abstract.
At a 40 percent management fee, an owner nets somewhere between $72,000 and $87,000 of that gross. At a 25 percent fee, comparable to the higher end of what a Rosemary Beach owner might negotiate, the same gross revenue nets $90,000 to $108,750. Even using the more generous 25 percent comparison, that's roughly $18,000 to $22,000 a year staying in the management company's account instead of the owner's, purely because of where the property sits.
Now put the insurance savings next to that number. A $4,000 to $5,000 annual insurance advantage doesn't come close to offsetting a management fee gap four to five times its size. The FORTIFIED discount is genuine. It's also the smaller number in this comparison, and it's the one that happens to be easiest to find on an insurance quote before an offer gets written.
The rental fee isn't the only place the math tilts against a pure cash-flow investor. A one-time capital contribution, reported in the $30,000 to $50,000 range depending on the source and the specific transaction, is due at closing on top of standard closing costs. Quarterly HOA dues run higher than a comparable Rosemary Beach single-family home, funding amenities like the Beach Club, Caliza Pool, and ZUMA Wellness Center, none of which generate rental revenue directly.
None of these costs are hidden exactly. They're disclosed in HOA documents and estoppel letters the way Florida law requires. But they rarely appear in the same conversation as the insurance quote, and an investor modeling returns off a spreadsheet built around premium savings alone is modeling the wrong side of the ledger.
None of this is an accident or a flaw in the system. Alys Beach restricts outside golf carts, requires advance approval for commercial photography, and keeps amenities like the Beach Club reserved for owners and their registered guests only. The mandatory rental program fits the same instinct: keep rental density controlled, keep the guest experience consistent, and keep the town feeling like it's run for owners first rather than optimized for turnover.
For a buyer who wants exactly that, a quiet, architecturally consistent, low-density retreat held for a decade or longer, the fee structure is simply the cost of the thing they're actually buying. The FORTIFIED construction that lowers insurance and the management structure that caps rental upside come from the same governing philosophy. You don't get one without the other.
If a rental income plan is part of why you're considering Alys Beach, ask the seller or listing agent for these before you go under contract:
A buyer optimizing for maximum rental cash flow and the flexibility to shop management companies will generally find that math favors Rosemary Beach, where the fee structure rewards active management and negotiation. A buyer who wants architectural durability, storm resilience, and a controlled, privacy-first environment, and who's comfortable treating rental income as a secondary benefit rather than the primary return, will find Alys Beach delivers exactly what it promises. Both are legitimate strategies. The mistake is choosing between the two towns using an insurance quote that only tells half the story.
Can an Alys Beach owner ever use a third-party property manager instead of the in-house program? Current reporting indicates no. Owners who want to rent their property are required to use the community's in-house management program, with no opt-out for independent management or self-listing through platforms like Airbnb or Vrbo. Confirm the current policy directly with the HOA before assuming otherwise, since community rules can be amended.
Does the FORTIFIED construction reduce flood insurance too, or only wind and hail? The reported 30 to 50 percent savings apply specifically to wind and hail premiums, which is where the masonry construction and impact-rated openings make the biggest structural difference. Flood insurance is a separate policy tied to FEMA flood zone designation, and much of the Alys Beach footprint sits in a zone that requires it regardless of construction type.
Is the one-time capital contribution the same for every Alys Beach lot? No. Reported figures vary by source and appear to depend on the specific parcel and transaction, generally landing between $30,000 and $50,000. Request the current fee schedule from the HOA before finalizing an offer rather than relying on a figure from an older listing or a comparable sale.
If you're weighing Alys Beach against Rosemary Beach or another stretch of 30A and want the actual numbers run against a specific property, the Bellville Team can pull current owner disclosures, rental actuals, and HOA documents before you write an offer. Start Your Coastal Journey.
Experience a level of service that goes beyond transactions. Whether you’re buying, selling, or exploring short-term rentals, we’re here to offer personalized insights and exclusive local expertise. Let’s collaborate to unlock your dream lifestyle on Santa Rosa Beach—because every connection brings you one step closer to the home you deserve.